HKEX phase 2 listing framework competitiveness review: Proposed reforms to notifiable transactions, connected transactions and spin-offs
The Stock Exchange of Hong Kong Limited (the “Stock Exchange”) proposes to allow consideration ratio to be calculated against higher of market capitalisation or net asset value and, raise the major transaction threshold from 25% to 50% for most transactions; remove the profits ratio; relax connected transaction and spin-off requirements; and enhance disclosure and board accountability.
Reforms form Phase 2 of the Stock Exchange’s listing framework competitiveness review, following Phase 1 reforms on listing eligibility concluded in July 2026.
Consultation period runs for 10 weeks and closes on Monday, 30 November 2026.
Overview
The Stock Exchange sets out the second phase of its listing framework competitiveness review in a consultation paper (the “Consultation Paper”) published on 21 September 2026.
Phase 1 of the review (concluded in July 2026) focused on broadening the diversity of companies eligible to list in Hong Kong.
Phase 2 of the Consultation Paper now turns to the post-listing regime–proposing targeted reforms to the requirements governing notifiable transactions, connected transactions and spin-offs.
The stated aim is to give listed issuers greater flexibility and cost efficiency in executing corporate transactions, while preserving robust investor protection through enhanced disclosure and stronger board accountability.
The major reforms proposed are detailed in the following three targeted parts:
Part 1: Notifiable transactions
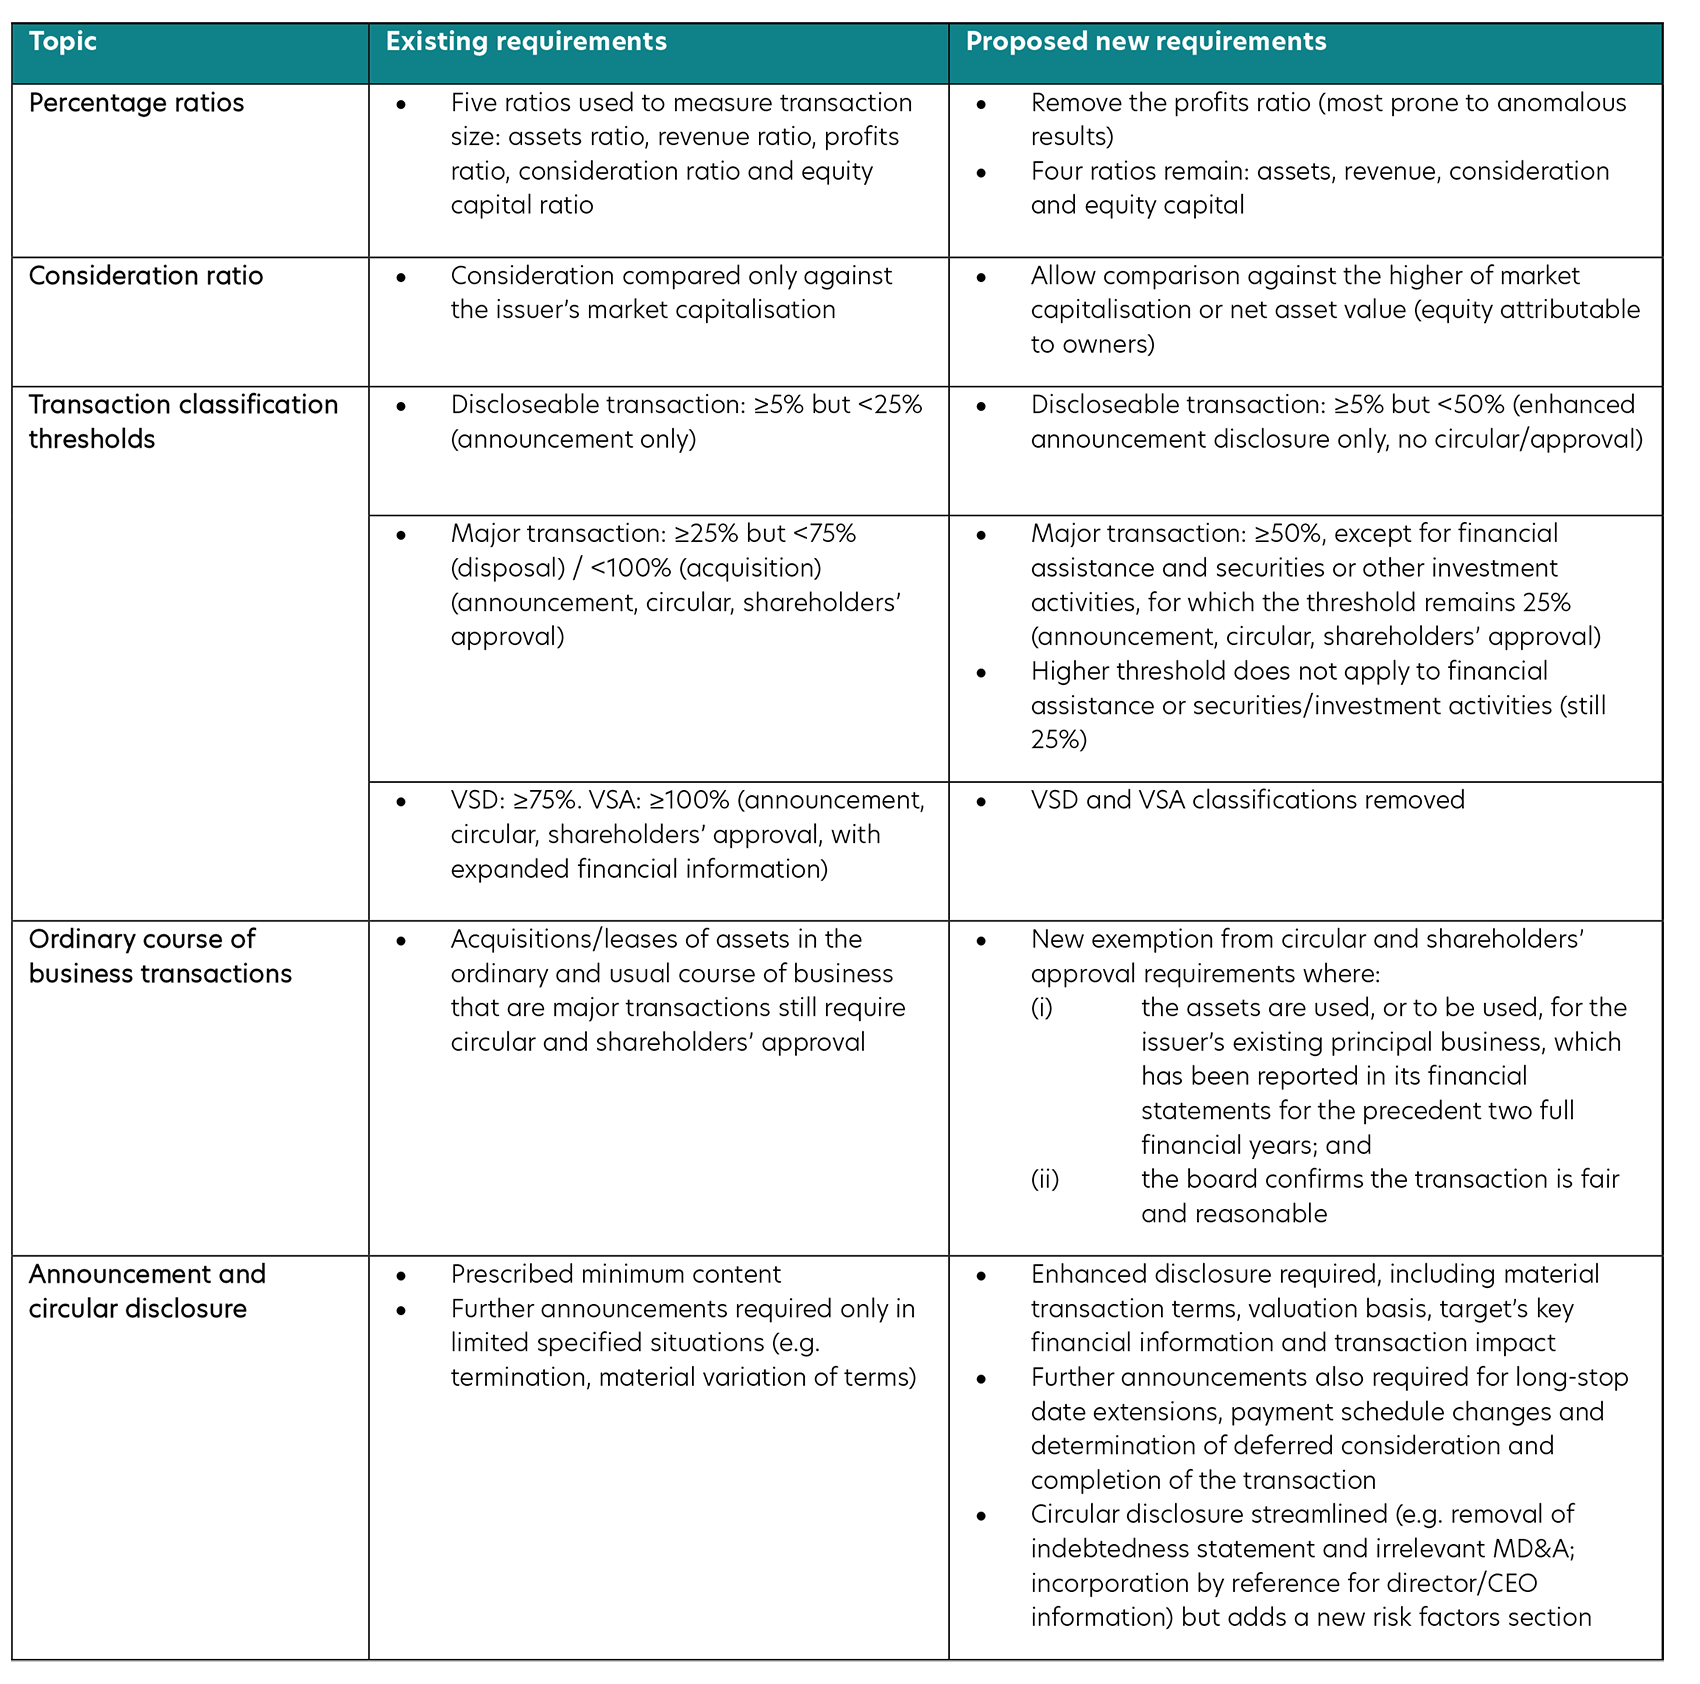
- Percentage ratios: removing the profits ratio, allowing consideration ratio to be measured against the higher of market capitalisation or net asset value, and raising the major transaction threshold from 25% to 50%, except for financial assistance and securities or other investment activities (with removal of the VSA/VSD classifications)
- Ordinary course transactions: a new exemption from circular and shareholders’ approval requirements for acquisitions or leases of assets used, or to be used, to maintain or expand the issuer’s existing principal business, subject to the prescribed two-year track record and board-confirmation requirements
- Enhanced disclosure: more detailed announcement and circular disclosure requirements for notifiable and connected transactions to offset the higher thresholds
Part 2: Connected transactions
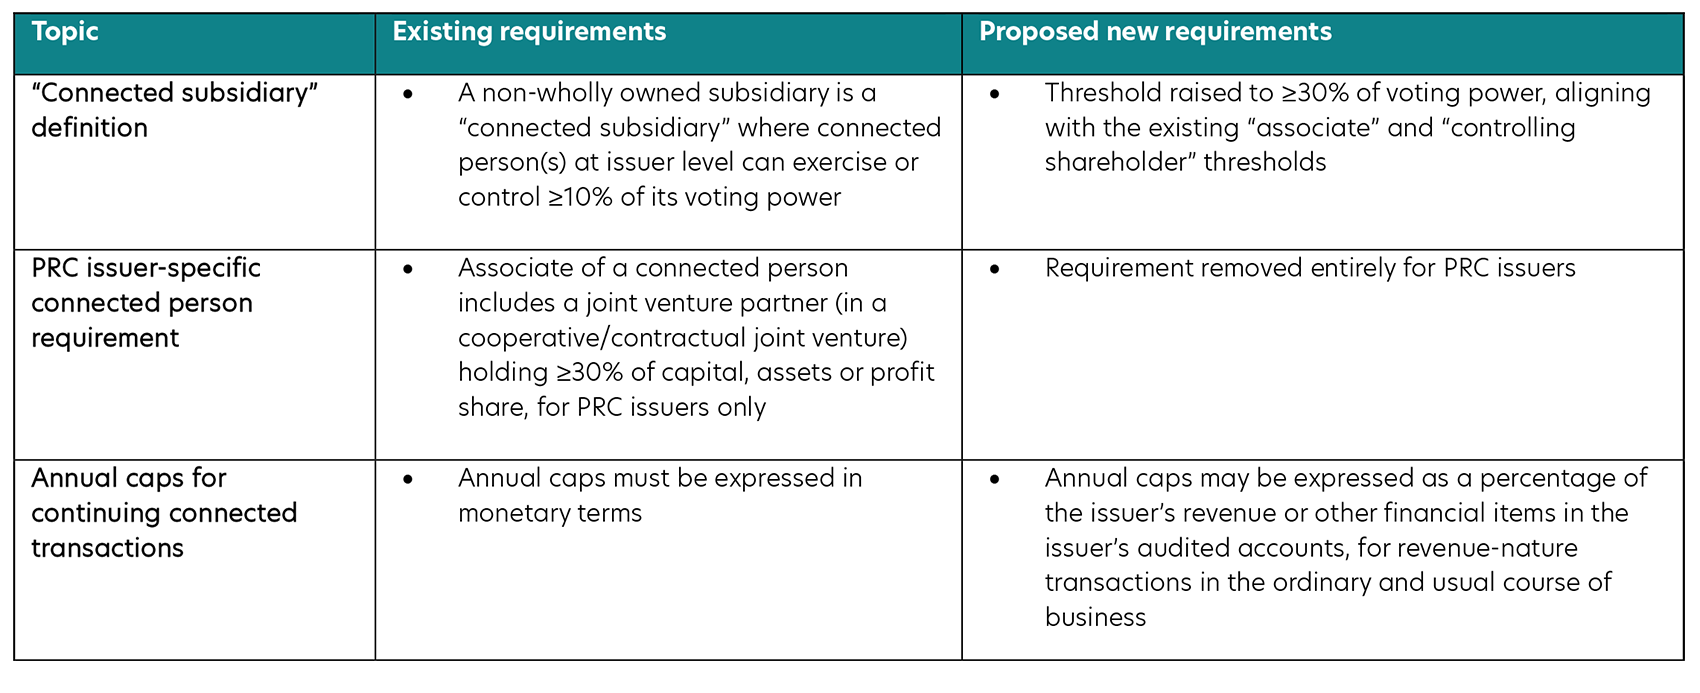
- Connected subsidiary: raising the “connected subsidiary” voting power threshold from 10% to 30%
- Percentage ratios: aligning the consideration ratio and disclosure approach with notifiable transactions
- Annual cap: allowing annual caps for certain continuing connected transactions to be expressed as a percentage of the issuer’s revenue or other financial items in its audited accounts, subject to disclosure and internal-control requirements
- PRC issuers: removing the PRC issuer-specific requirement that treats certain joint venture partners of connected persons as associates
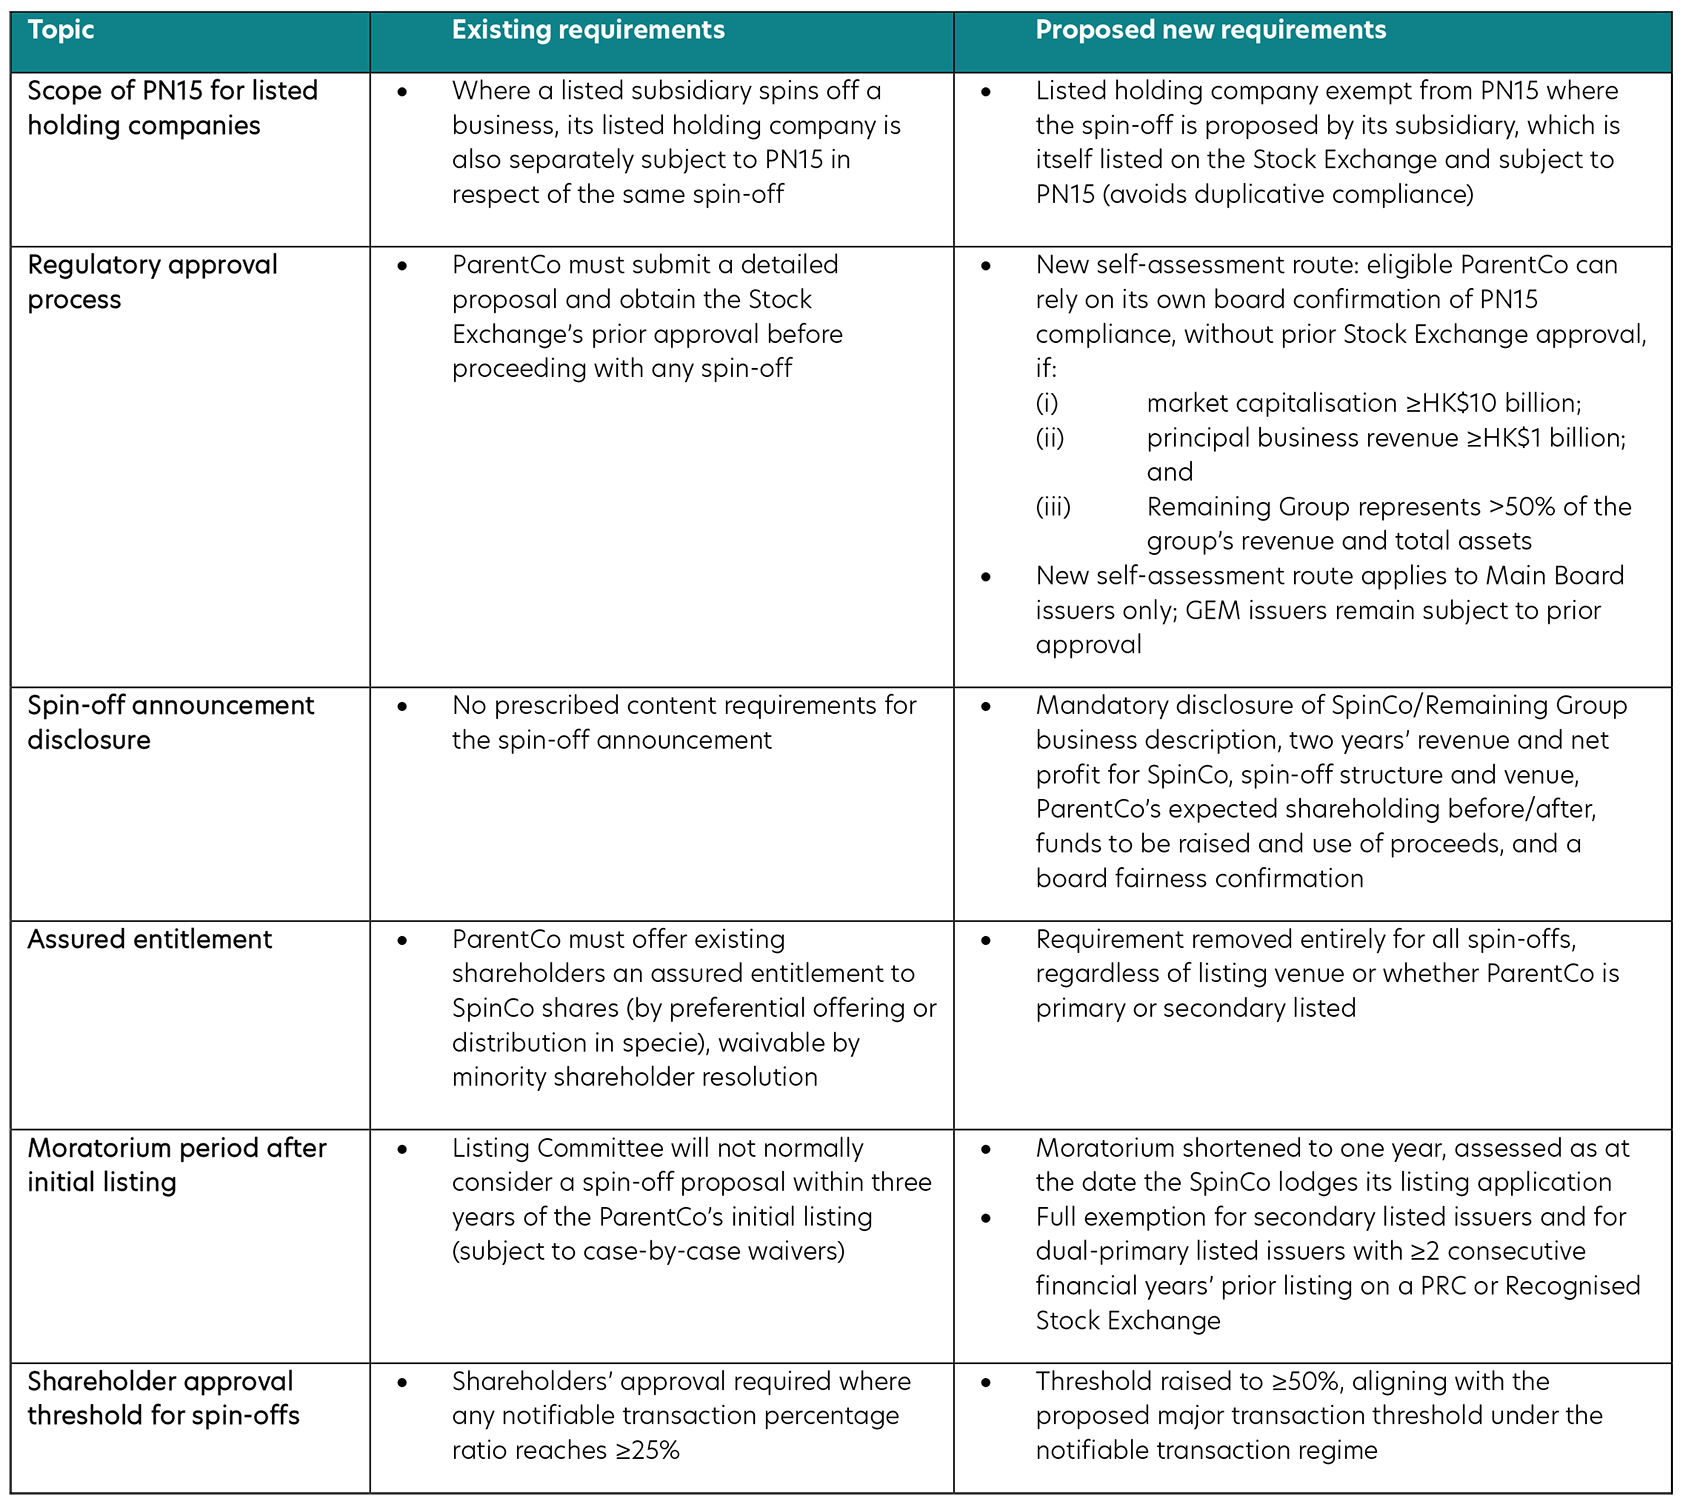
Part 3: Spin-offs
- Regulatory process: introducing a self-assessment route (no prior Stock Exchange approval) for eligible Main Board issuers meeting the prescribed market capitalisation, revenue and remaining group requirements
- Assured entitlement: removing the assured entitlement requirement
- Moratorium period: shortening the moratorium period from three years to one year (with exemptions for secondary and dual-primary listed issuers)
The consultation period runs for ten weeks and closes on Monday, 30 November 2026. Subject to consultation feedback, the Stock Exchange proposes that the changes take effect shortly after publication of the consultation conclusions.
Comparison table of existing requirements and proposed new requirements
The tables below summarises, in brief, the existing Listing Rule requirements and the corresponding new requirements proposed in the Consultation Paper. It is not exhaustive; readers should refer to the Consultation Paper for full details, rationale and the specific consultation questions.
Part 1: Notifiable transactions
Part 2: Connected transactions
Part 3: Spin-offs (PN15)